AI and Cloud-Native Architecture: The Future of Enterprise Banking
AI can improve how banks acquire, serve and retain customers, but only when it is connected to secure, cloud-native banking and payment infrastructure.
Artificial intelligence is changing customer expectations in banking. Customers increasingly expect financial services to be immediate, personalised and available in the channel they already use. Banks, meanwhile, need to improve efficiency, launch products faster and meet demanding security and regulatory obligations.
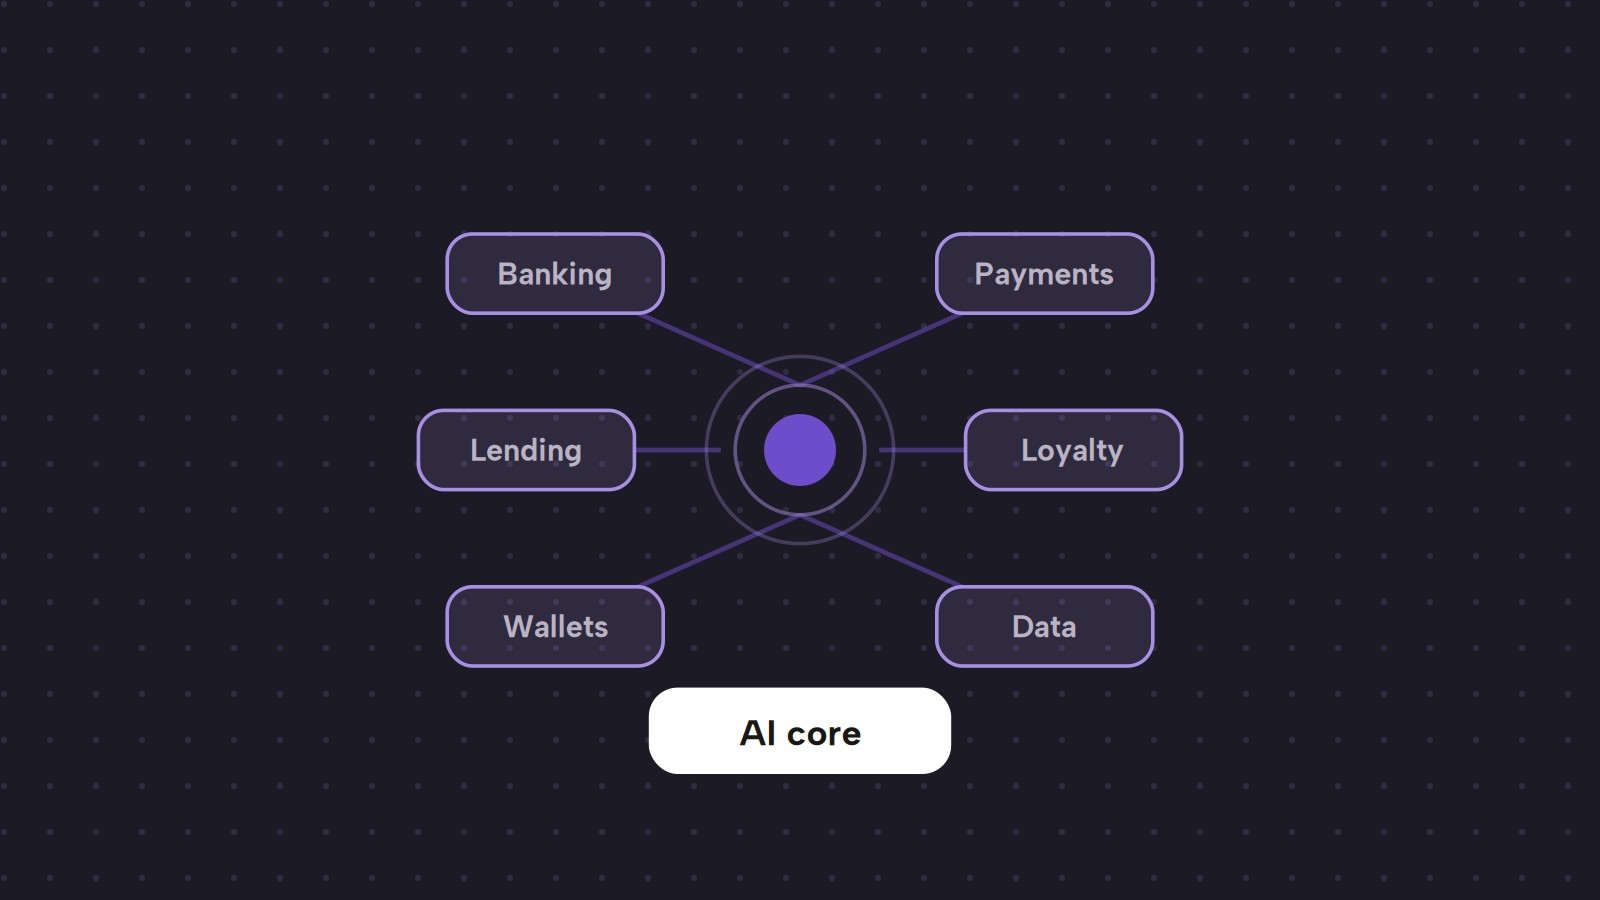
AI can help achieve those goals, but an AI model on its own is not a banking transformation strategy. Its value depends on the systems, data and controls around it. When customer information is fragmented across legacy applications, even sophisticated AI has an incomplete view of the customer. Cloud-native architecture provides the connective foundation that allows intelligence to be used safely across onboarding, payments, servicing, lending, loyalty and customer engagement.
What cloud-native banking changes
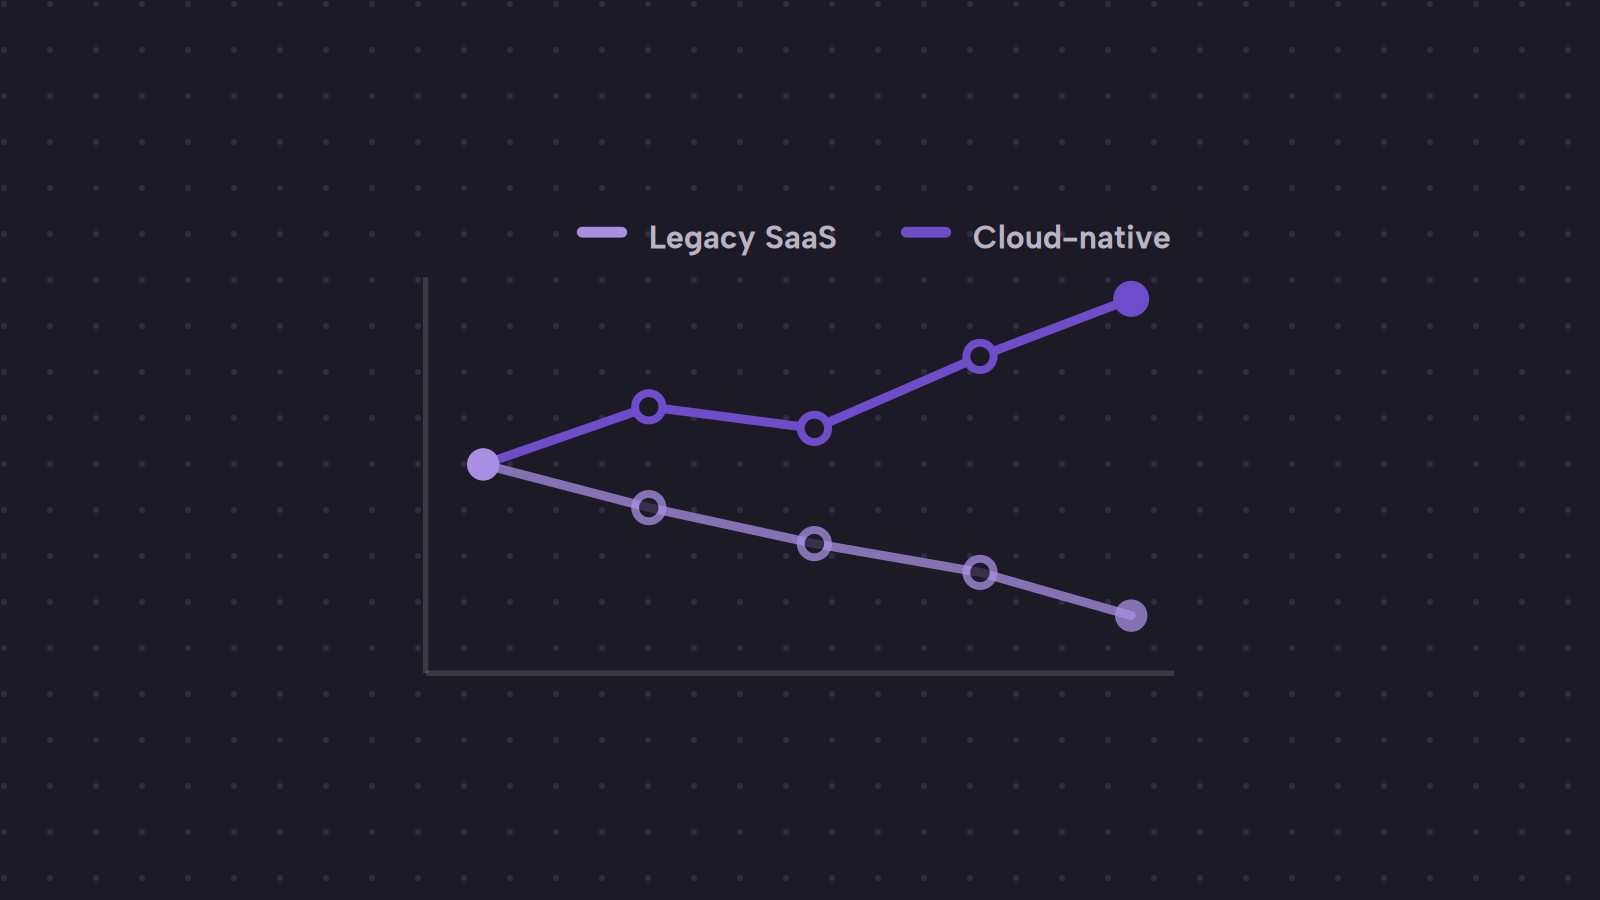
Cloud-native architecture breaks large, tightly coupled systems into modular services connected through secure APIs. A bank can introduce a new customer experience or capability without replacing every underlying system at once. Individual services can be configured, deployed and scaled according to demand while the bank retains control over integration, security and data.
For established institutions, this creates a practical path to modernisation. The core banking system can remain the system of record while a digital experience layer handles onboarding, accounts, cards, wallets, payments and customer engagement. New services can be introduced progressively, reducing the risk of a single large-scale replacement programme.
Where AI creates practical value
AI becomes useful when it is embedded in real operating journeys rather than added as a standalone chatbot. Relevant applications include:
- guiding applicants through digital onboarding and identifying missing information;
- helping service teams understand a customer's account and transaction history;
- detecting behavioural signals that may indicate churn or disengagement;
- recommending the next best product, message or reward for an individual customer;
- prioritising exceptions and cases that require human review; and
- identifying unusual activity for further investigation.
These capabilities should support controlled decisions, not create an unaccountable black box. High-impact actions require defined permissions, traceable inputs, audit records and clear escalation to a person.
One view of the customer
The quality of an intelligent experience is constrained by the quality and accessibility of its data. A customer may hold an account, card and wallet, interact with merchants, receive rewards and contact support. If those activities sit in disconnected systems, the organisation cannot respond consistently.
A shared platform can connect customer, transaction and engagement events. That allows an intelligent agent to recognise context: whether onboarding is incomplete, a card has been declined, a customer has become inactive or a relevant benefit is available. The result is a more useful interaction and a better basis for customer retention.
Security, governance and human control
Enterprise AI must operate within the same disciplines expected of financial infrastructure. Access should be role-based, sensitive data protected in transit and at rest, and actions recorded for audit. Models and rules should be monitored for accuracy, bias and unintended outcomes. Institutions also need clear policies defining which decisions can be automated and which require human approval.
Cloud deployment does not remove regulatory responsibility. Architecture must support the organisation's requirements for resilience, data residency, privacy, business continuity and third-party oversight. The right deployment pattern will depend on the institution and its markets.
A progressive route to modernisation
Banks do not need to transform every system before creating value. A sensible programme begins with a defined customer or operational outcome, connects the data required for that outcome, and introduces a modular service with measurable controls. Successful capabilities can then be extended across more products and journeys.
How Youtap solves this
Youtap provides the connected architecture required to turn AI into practical banking outcomes. Its six modules—YouBank, YouPay, YouAccept, YouTravel, YouReward and YouShop—operate on a shared cloud-native platform and can be deployed individually or together.
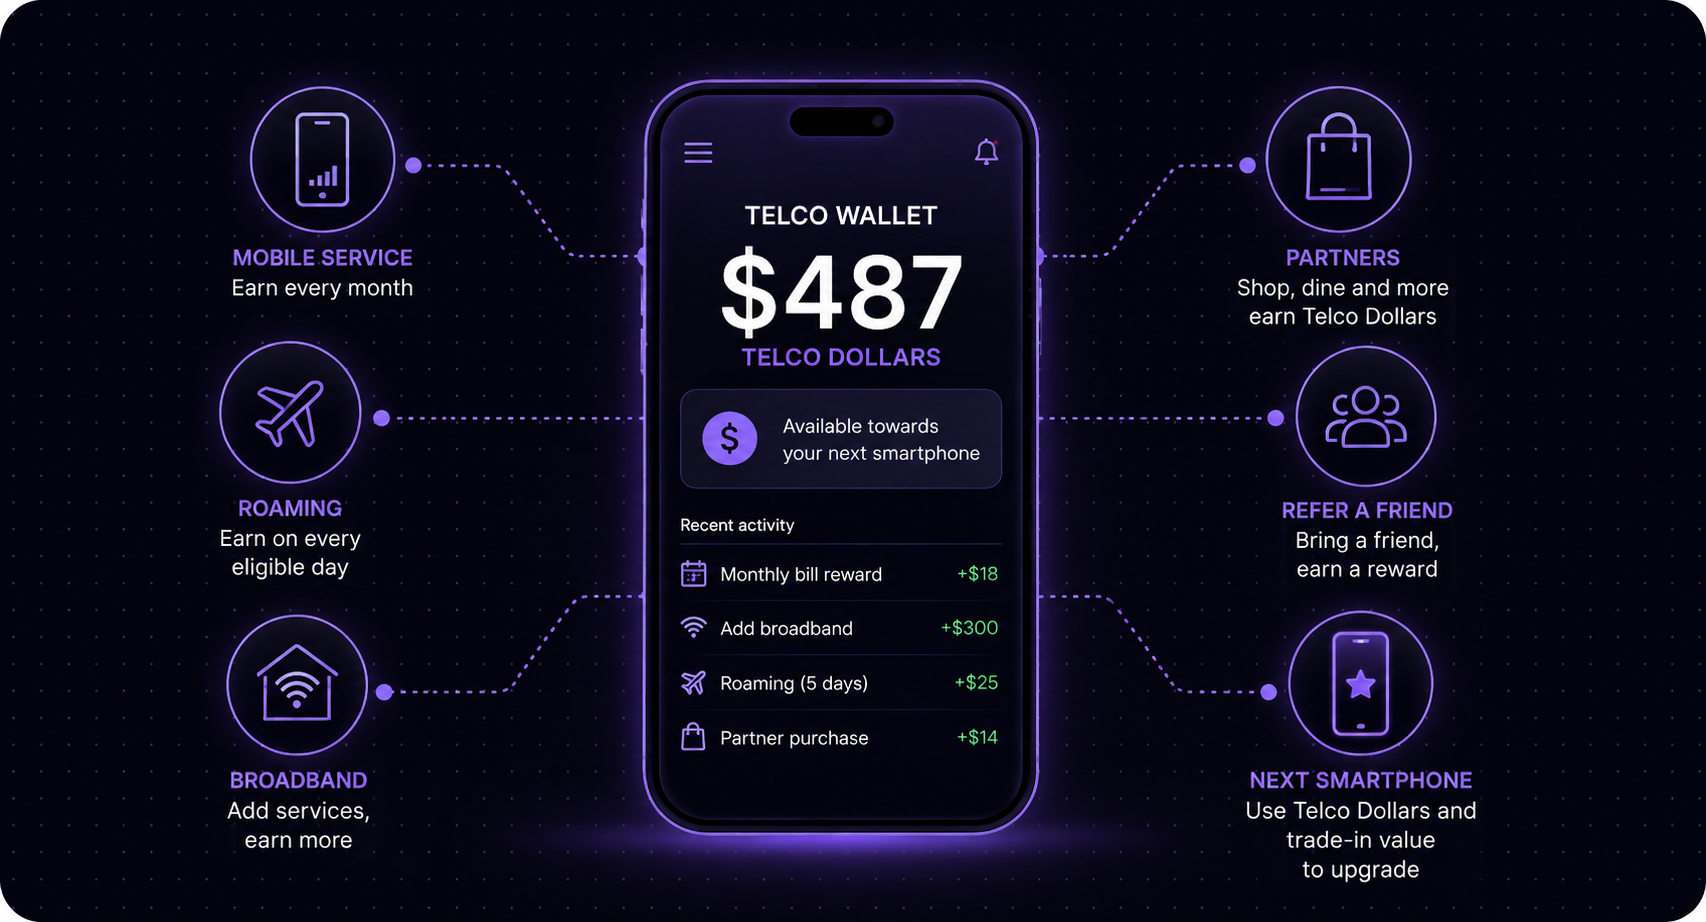
YouBank provides digital onboarding, accounts, cards and loan-origination journeys. YouPay connects branded wallets and payment services. YouReward uses customer, transaction and engagement signals to support personalised campaigns, next-best actions and retention programmes. YouAccept and YouShop extend the same customer and transaction environment into merchant acceptance and commerce.
Youtap's intelligent agents work across these capabilities rather than sitting outside them as a generic chatbot. They can guide onboarding, identify incomplete applications, support customers using account context, recognise churn signals and recommend relevant actions. Secure APIs connect the platform with an institution's existing core banking, CRM, identity, credit and payment systems, while role-based access, audit trails and human approval controls help the institution retain control of decisions, policies and customer data.