Build or Buy Your Payments Platform? An Honest Answer
The real payments-platform decision is rarely build versus buy. It is deciding which capabilities create differentiation and which should be sourced from a proven platform.
The build-or-buy debate is often presented as a choice between control and speed. Build, and the organisation owns its destiny. Buy, and it launches sooner. In practice, that framing is too simple. A payments platform is not a single application: it is a collection of regulated, interconnected capabilities that must remain secure and available while products, schemes, fraud patterns and customer expectations continue to change.
For most organisations, the strongest answer is selective ownership. Build the experiences and capabilities that genuinely differentiate the business. Use proven platform components for the infrastructure that must work reliably but does not create unique customer value.
What building really involves
An internal team can design precisely for the organisation's operating model. It can control the roadmap, data model and customer experience. For a business with specialist requirements, substantial engineering capability and a long investment horizon, that control may be justified.
But the initial software build is only part of the cost. A production payments platform also requires security engineering, environments, monitoring, resilience, reconciliation, dispute and exception handling, reporting, scheme and regulatory change, certification, documentation and continuous support. These obligations continue after the first product launches.
The largest risk is often opportunity cost. Skilled teams can spend years rebuilding commodity infrastructure while competitors focus on distribution, partnerships and customer growth.
What buying does and does not solve
A proven platform can provide tested services, established operating patterns and a faster route to market. It may include digital wallets, payment processing, merchant acceptance, cards, settlement, APIs and operational tooling. That reduces the number of foundational components the organisation needs to create and maintain itself.
Buying does not remove responsibility. The organisation still needs a clear proposition, integration architecture, customer journeys, operating processes, risk policies and governance. A product that is fast to install but difficult to configure or integrate can simply move cost from engineering into operations.
The questions that matter
Before selecting an approach, decision-makers should ask:
- Which capabilities are genuinely distinctive to our strategy?
- What must we launch in the next 6, 12 and 24 months?
- Which existing core, CRM, identity and data systems must remain?
- What transaction volumes, markets, currencies and payment methods must be supported?
- Which security, regulatory, resilience and data-residency obligations apply?
- Can the platform be configured without creating a permanent custom-code branch?
- Who owns customer data, operational data and integration interfaces?
- What is the five-year cost, including people, change and operations—not only licence fees?
Why a modular model is usually stronger
A modular platform allows an organisation to deploy the capabilities it needs and integrate them with existing systems through APIs. It can retain a core banking or payment system while adding a modern wallet, merchant channel or customer engagement layer. Additional capabilities can be introduced without repeating the entire integration programme.
This approach also protects strategic freedom. The institution can own its brand, propositions, data policies and customer experience while relying on maintained infrastructure for common services.
The honest answer
Build where ownership creates a durable competitive advantage. Buy where the requirement is complex, regulated and broadly common across the industry. Combine the two through an architecture that preserves portability and control.
How Youtap solves this
Youtap provides the maintained platform capabilities that organisations should not need to rebuild, while preserving their ownership of the customer proposition, brand and strategic roadmap. The platform is modular: YouPay provides wallets and payment services; YouAccept provides merchant onboarding, acceptance, acquiring and settlement; YouBank provides digital banking and loan origination; YouReward provides loyalty and customer engagement; YouShop provides merchant commerce; and YouTravel provides multi-currency wallet and travel-card capabilities.
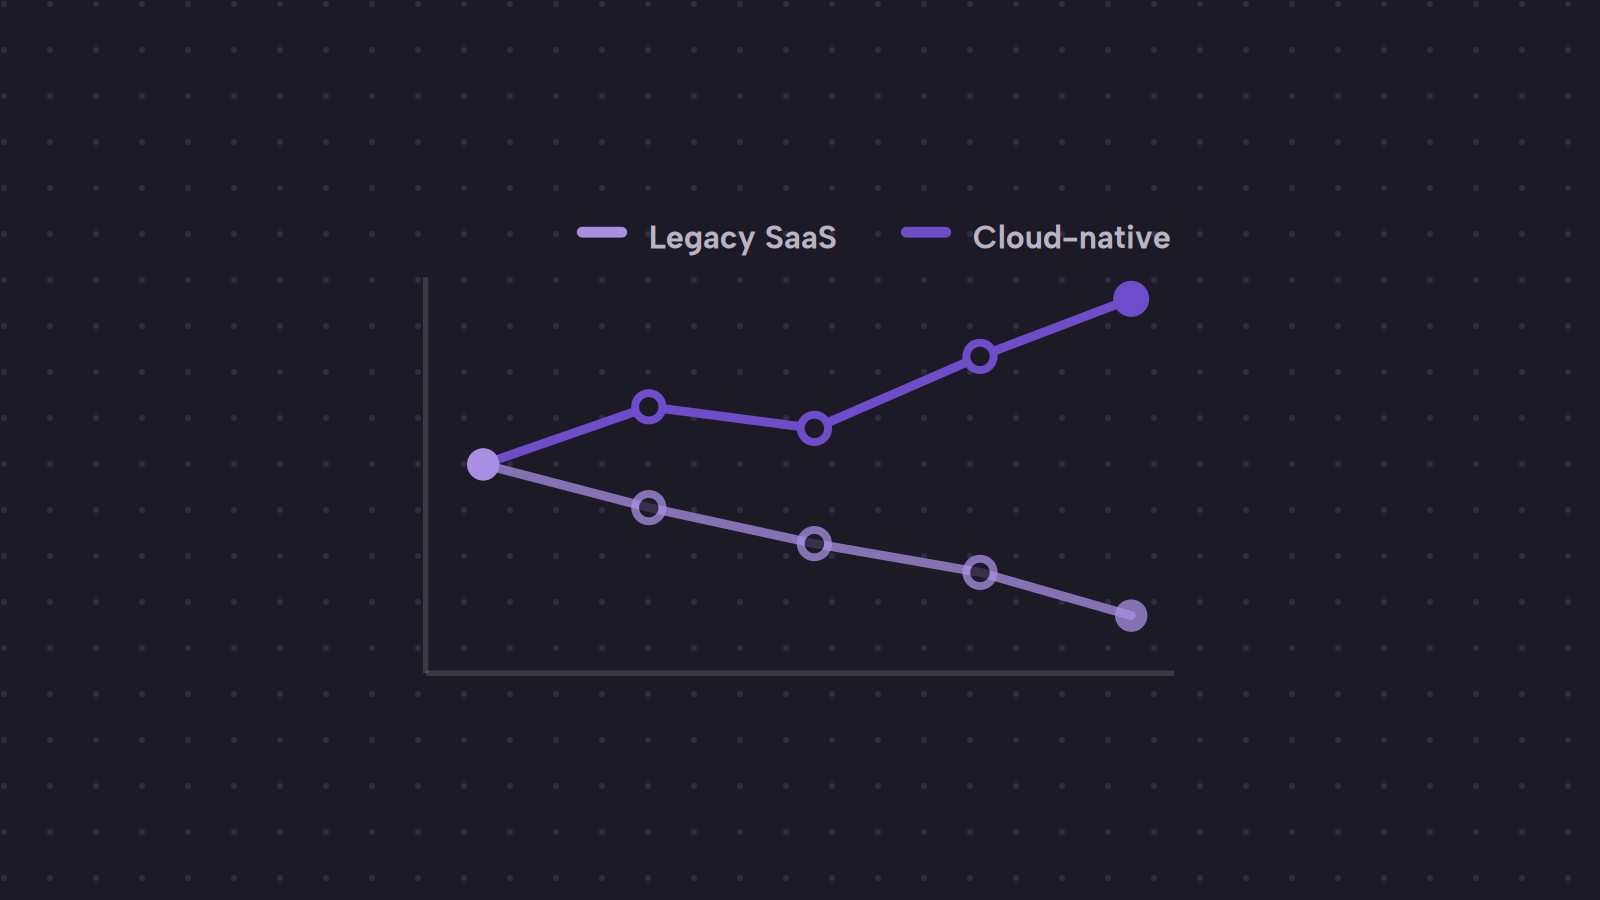
An organisation can deploy one module to solve an immediate requirement or combine multiple modules through the shared cloud-native architecture. Secure APIs connect Youtap with existing core banking, payment, CRM, identity, fraud, credit and data systems. Configuration supports product, brand and market variations without forcing the institution to maintain a separate custom platform for each launch.
This gives the organisation a practical hybrid model: buy regulated and operationally intensive infrastructure from Youtap, build the differentiating journeys and propositions it chooses to own, and integrate both with its existing enterprise environment.