The digital wallet as your customer's financial home
A payment feature is a tool; a financial home is a relationship. Why the wallet's real power is becoming the place a customer's financial life lives.
Most organisations think about a wallet as a way to take payments. That’s the smallest version of what a wallet can be, and treating it that way leaves most of the value on the table. The wallet’s real power isn’t that it processes a transaction. It’s that it can become the place a customer goes first for anything to do with their money — the financial home they open out of habit. An institution that builds the payment feature has a tool. An institution that builds the financial home has a relationship that’s very hard to take away.
The difference between a feature and a home
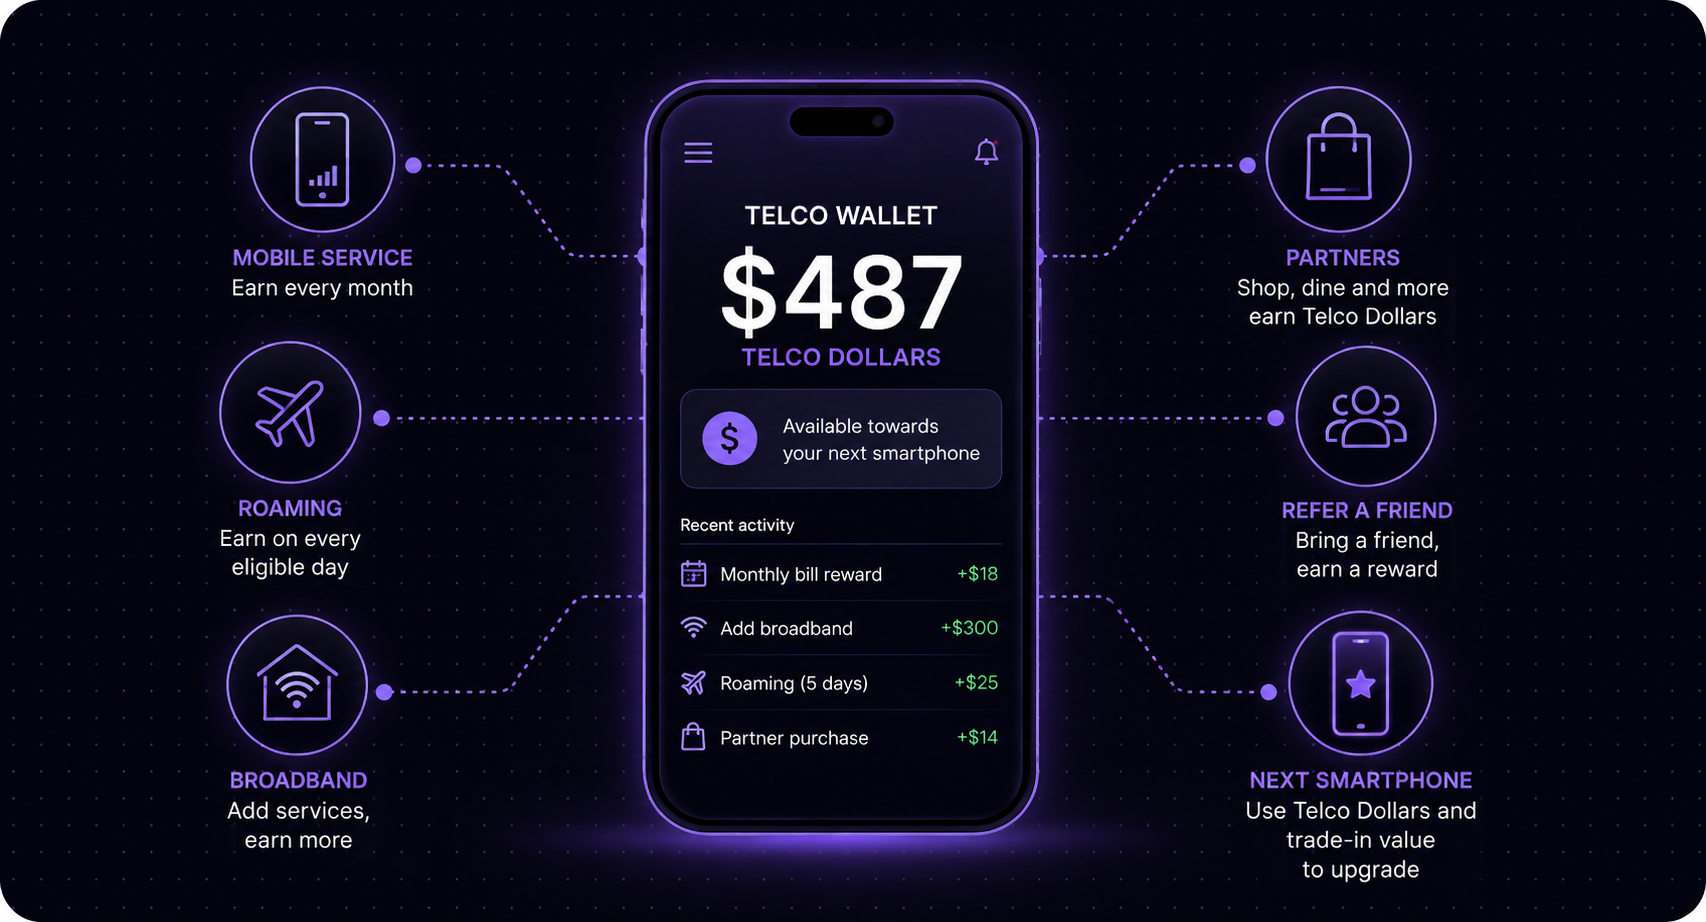
A payment feature does one job: it moves money when the customer wants to pay. The customer uses it and closes it. There’s no reason to open it otherwise, no habit, no daily presence in their life. A financial home is different. It’s where the customer checks their balance, pays a bill, splits a cost with a friend, tops up, redeems a reward, sees what they spent, and increasingly does more — savings, credit, insurance, whatever the institution chooses to add. The customer opens it not because they’re paying, but because it’s where their financial life lives.
That habit is the whole game. A customer who opens your wallet daily is a customer who is yours in a way a once-a-month payment user never is.
Why this is the direction the market is moving
This isn’t speculation — it’s the clear trend in how financial services are being delivered. Embedded finance, where financial services live inside the apps and brands people already use rather than in a separate banking app, has moved from the edge to the mainstream. The market has grown into the hundreds of billions and is forecast to keep climbing, precisely because customers prefer their financial services where they already are rather than scattered across separate apps. The brands winning are the ones becoming the place financial life happens, not the ones offering one more standalone payment method.
The logic extends across every sector. A bank wants to be the customer’s primary financial relationship rather than one of several apps. A telco that’s already the most-used app a customer has is positioned to absorb financial life into that relationship. A retail group wants its customers spending, earning, and managing value inside its ecosystem rather than a competitor’s. In every case, the wallet-as-home beats the wallet-as-feature.
What turns a wallet into a home
Three things separate a wallet people live in from one they ignore.
The first is breadth — enough useful things to do that there’s always a reason to open it. Payments alone aren’t sticky; payments plus rewards plus bill pay plus the ability to add new services over time is what creates daily relevance.
The second is value the customer can feel and use immediately. Rewards they can spend like cash, balances that are genuinely useful, redemption that’s frictionless. A wallet that hoards value the customer can’t easily use isn’t a home; it’s a holding pen they resent.
The third is that everything connects. The reason a wallet becomes a home is that paying earns rewards, rewards are spendable in the same place, spending generates the data that personalises the next offer, and the whole thing reinforces itself. A wallet built as a single feature can’t do this. A wallet built as an integrated platform can.
What this means for you
If you’re treating a wallet as a payment feature, you’re building the least valuable version of it. The opportunity is to build the place your customers’ financial life happens — the app they open out of habit, the relationship that compounds, the ecosystem that gets stickier the more they use it. That’s not a bigger payment feature. It’s a different ambition, and it requires a platform built to be a home rather than a transaction.
The wallet is the most direct route a bank, telco, or retailer has to becoming the centre of a customer’s financial life. The ones who see it as more than a payment method are the ones who’ll get there.
Youtap Technology Limited provides white-label digital wallet platforms built to be the centre of your customers’ financial life — payments, rewards, and more, integrated under your brand. Explore the Digital Wallet platform →