Why Banks Should Own the Travel Wallet Experience
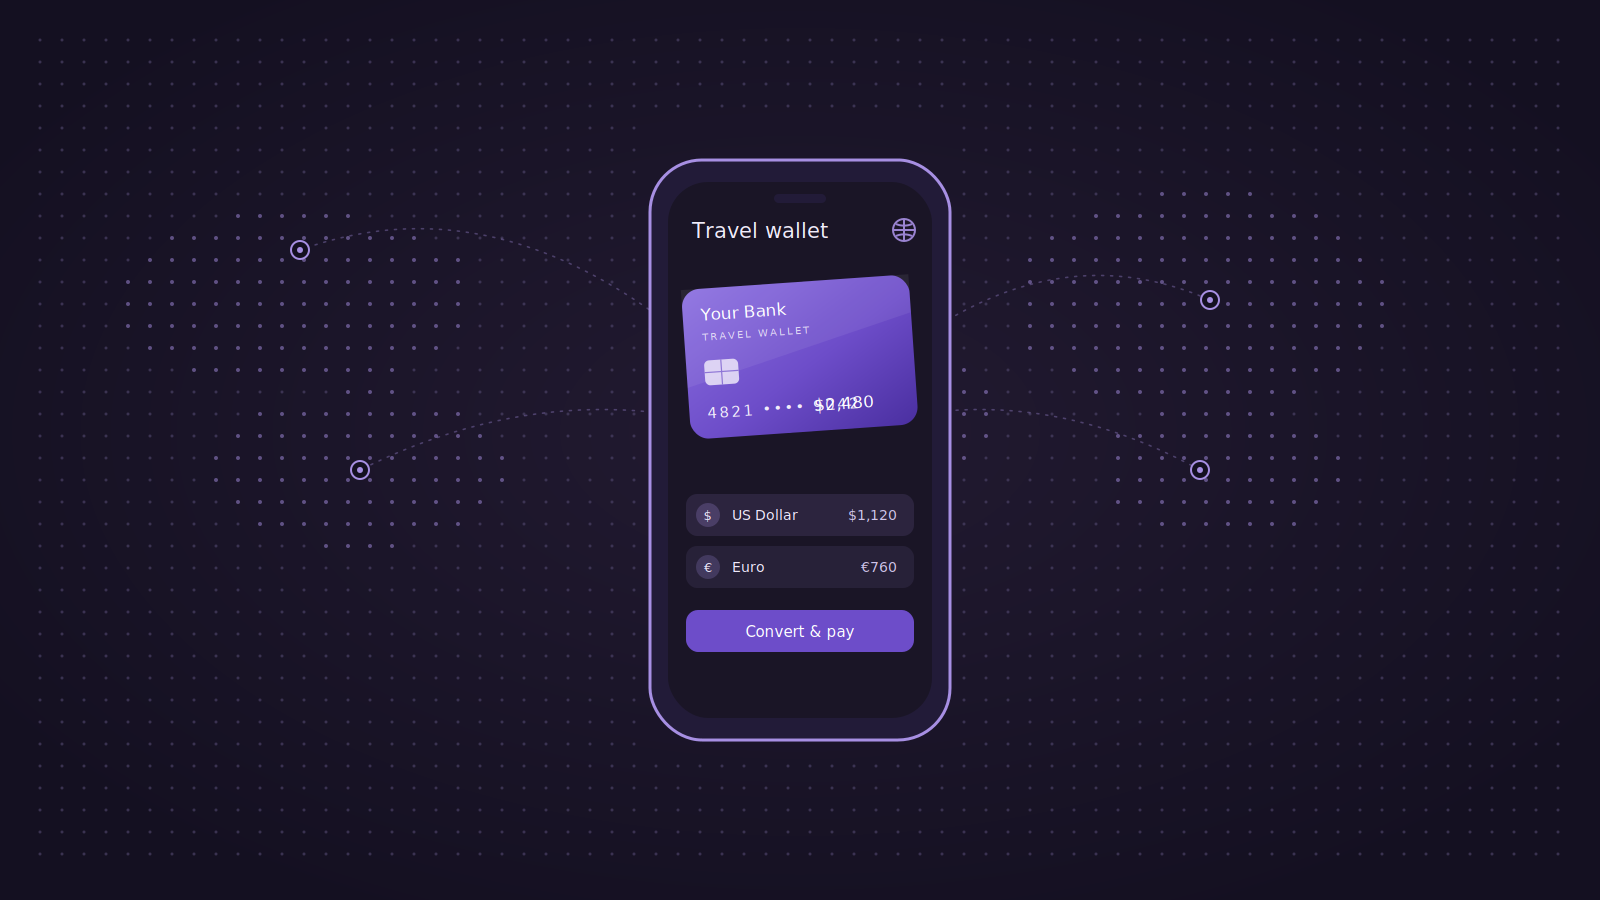
Travel has changed dramatically over the past decade. Customers no longer want to visit a branch to buy foreign currency or carry multiple prepaid travel cards. They expect to manage everything from their banking app—exchange currencies instantly, receive a virtual card, control spending in real time, and receive transaction notifications anywhere in the world.
Travel has changed dramatically over the past decade. Customers no longer want to visit a branch to buy foreign currency or carry multiple prepaid travel cards. They expect to manage everything from their banking app—exchange currencies instantly, receive a virtual card, control spending in real time, and receive transaction notifications anywhere in the world.
For banks, this presents an important strategic decision: should they direct customers to a third-party travel fintech, or should they offer their own branded travel wallet?
The Modern Travel Wallet Is More Than a Card
A modern travel wallet brings together multicurrency accounts, foreign exchange, physical and virtual cards, spending controls, travel notifications, rewards, and security into a single digital experience.
Travel also represents one of the most active periods in a customer's financial life. Before travelling, customers exchange money and plan budgets. During their trip, they make frequent purchases, manage cards and monitor spending. After returning home, they reconcile transactions and convert unused balances.
Every interaction strengthens the relationship between the customer and whichever platform they use.
The Real Competition Is Customer Engagement
Many banks evaluate travel products based on card fees or foreign exchange margins. While these metrics matter, they overlook a much bigger opportunity.
The real question is:
Who owns the customer relationship while they are travelling?
When customers rely on an external travel app, that provider becomes their daily financial companion. Over time, those platforms often expand into insurance, rewards, international transfers and other financial services, gradually reducing the bank's role in the customer's financial journey.
Banks Don't Need to Build Everything
Owning the customer experience doesn't mean building an entire travel platform from scratch.
Many financial institutions are choosing enterprise-grade white-label platforms that integrate into their existing mobile banking applications, allowing them to maintain their own brand while accelerating time to market.
This approach enables banks to:
Deliver branded multicurrency wallets
Issue physical and virtual travel cards
Integrate with existing banking, card and FX systems
Maintain ownership of customer data and engagement
Continuously introduce new travel services without replacing core banking systems
The Youtap YouTravel Platform
Youtap's YouTravel Platform has been designed specifically for financial institutions that want to deliver a modern travel wallet under their own brand.
Rather than replacing existing banking infrastructure, YouTravel integrates with core banking, card management, foreign exchange, loyalty and digital banking systems through secure APIs and enterprise integration capabilities. It supports multicurrency wallets, physical and virtual cards, real-time card controls and scalable international payment services.
One example is Bangkok Bank's Travel Card, where Youtap provides the underlying technology while Bangkok Bank maintains full ownership of the customer experience and relationship.
Looking Ahead
Travel wallets are rapidly evolving beyond simple foreign currency products. Future capabilities are expected to include personalised offers, integrated travel insurance, AI-powered travel assistance, sustainability insights, loyalty integration and cross-border account-to-account payments.
Banks that own their travel platform will have the flexibility to introduce these innovations as customer expectations evolve, without relying on the roadmap of an external consumer fintech.
Final Thoughts
The decision is no longer just about offering a travel card.
It's about deciding who owns one of the most valuable customer engagement opportunities in modern banking.
With enterprise platforms like Youtap YouTravel, banks can deliver world-class multicurrency travel experiences under their own brand while retaining the customer relationship, valuable first-party data and long-term strategic control.